The New Investment Law and Intellectual Property: Shorter Procedures, a Bigger Role for Intangible Assets
ISSUE 1 – OCTOBER 2026
1. Background:
In December 2025, the National Assembly passed a package of closely related laws. The Law on Investment No. 143/2025/QH15 took effect on 1 March 2026, replacing the 2020 Investment Law, with the conditional business list provisions applying from 1 July 2026. On 1 April 2026, two further laws took effect: the amended Law on Intellectual Property No. 131/2025/QH15 and the amended Law on Technology Transfer No. 115/2025/QH15.
There has since been a further change. The National Assembly passed Law No. 24/2026/QH16 on 24 August 2026, amending the Investment Law. The President promulgated by order on 10 September 2026. It takes effect on 1 March 2027, replaces Appendix IV in full, and reduces the conditional list to 137 business lines. The new list adds several emerging sectors, including crypto asset services, data exchange services and personal data processing services.
Taken separately, each law reforms only its own area. Read together, they change two things that matter directly to foreign investors. First, market entry is faster and involves fewer procedural steps than before. Second, a patent, a trademark or proprietary technology can now take a direct part in the investment structure, rather than remaining a passively protected asset.
Turning to the implementing instruments, Decree No. 96/2026/ND-CP guides the Investment Law and was both issued and brought into force on 31 March 2026, replacing Decrees 31/2021, 19/2025 and 239/2025. Decree No. 100/2026/ND-CP and Circular No. 10/2026/TT-BKHCN guide the IP Law. Decree No. 101/2026/ND-CP guides the Technology Transfer Law.
2. Where the Procedural Bottlenecks Have Been Removed
This is the most visible group of changes. The general thrust of the 2025 Investment Law is to shift the focus of state management from pre-approval to post-inspection: fewer licensing steps before implementation, more inspection during operation. Five groups of amendments carry that through.
2.1. Incorporate first, obtain the Investment Registration Certificate later
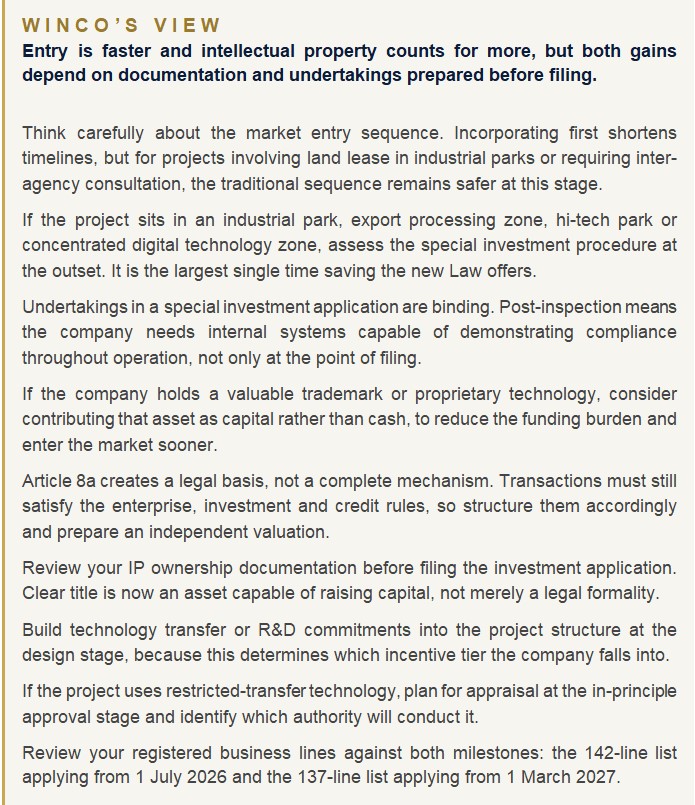
This is the most significant change to the sequence. Previously, a foreign investor wishing to establish a new company in Vietnam was required to have an investment project and obtain an Investment Registration Certificate first, and only then carry out enterprise establishment procedures. Clause 2, Article 19 of the 2025 Investment Law reverses that sequence: a foreign investor may establish an economic organisation to implement the project before carrying out the procedures for issuance or amendment of the Investment Registration Certificate.
The accompanying condition is that, when carrying out establishment procedures, the investor must still satisfy the market access conditions under Article 8 of the Law. In other words, the Law removes the sequencing requirement, not the substantive one.
The practical significance is clear. Having legal personality early means the company can open a bank account, sign an office lease, recruit staff and carry out preparatory work, instead of waiting for the entire investment procedure to conclude before it can act. For an investor weighing Vietnam against other countries in the region, this is a meaningful time saving.
2.2. A narrower set of projects requiring in-principle investment approval
Article 24 of the 2025 Investment Law sets out an express list of 20 project types subject to in-principle investment approval, replacing the broad and hard-to-apply formulation used previously. Approval authority has also been devolved to the local level, with the powers of the Chairman of the provincial People’s Committee significantly expanded.
For investors, the greatest value of this change is predictability. Before incurring the cost of preparing an application, a company can check its project against the list of 20 project types and establish with reasonable certainty whether in-principle approval is required.
2.3. The special investment procedure for projects inside industrial and economic zones
Article 28 of the 2025 Investment Law establishes a special investment procedure for the first time, guided in detail by Articles 46 to 50 of Decree 96/2026. Under that mechanism, an investor may elect special investment registration for projects located in industrial parks, export processing zones, hi-tech parks, concentrated digital technology zones, free trade zones, international financial centres and functional zones within economic zones. Projects subject to in-principle investment approval cannot use this mechanism.
The heart of the mechanism is how the application is prepared. Instead of obtaining separate licences or approvals for construction design, environmental impact assessment and fire safety, the investor submits a registration dossier accompanied by a written undertaking to meet the applicable conditions, standards and technical regulations. State authorities verify compliance at a later stage.
This replaces licensing with registration. It shortens timelines considerably, but it also shifts risk onto the company. An undertaking that proves inaccurate, or that the company fails to honour, will be dealt with at the post-inspection stage, by which point the project is under way and the cost of remediation is far higher.
2.4 Reduction of conditional business lines
Compared with the 2020 Investment Law, Appendix IV of the 2025 Investment Law cut 38 conditional business lines and adjusted the scope of 20 others. Business lines removed from the list include tax procedure services and customs procedure services.
Article 7 of the Law further requires the Government to publish two separate lists: one of business lines that genuinely require a licence or certificate before operation, and one of business lines that move from licensing to published conditions, managed through post-inspection. This is the clearest expression of the shift in regulatory thinking.
The reduction is continuing in two steps, and the baseline matters, because the published figures are easy to confuse. Appendix IV of Law No. 143/2025/QH15 contained 198 business lines. In the first step, Resolution No. 66.17/2026/NQ-CP cut that list to 142 business lines, applicable from 1 July 2026. In the second step, Law No. 24/2026/QH16 cut 62 business lines and amended 14, measured against the 2025 Investment Law, while adding one new line, namely visa support services provided by authorised business establishments. The result is a list of 137 business lines from 1 March 2027, which is expected to eliminate around 786 business conditions and simplify 232 administrative procedures.
2.5 Electronic filing
Decree 96/2026 allows investment applications to be submitted electronically with a digital signature, carrying the same legal effect as hard copies. The investor is responsible for consistency between the paper and electronic versions. It should be noted that online submission is only available once the national investment information system meets operational requirements, so in practice a company should still be ready to file in hard copy.
3. The Potential New Role of Intellectual Property in Investment Activity
Article 8a: IP rights enter investment transactions. The amended IP Law adds an entirely new Article 8a. Clause 2 permits the owner to use its IP rights to carry out civil, commercial and investment transactions. Clause 3 provides that the State encourages the exploitation of IP rights, including their use for capital contribution or as a mortgage to secure loans, in accordance with the laws on investment, enterprise and credit.
This provision needs to be read carefully, because it is easy to overstate. Article 8a is a policy provision that creates a legal basis; it is not self-executing. The Law creates the opening, but each transaction must still comply with the rules on enterprise, investment and credit. Whether a bank will accept a trademark as mortgage security, and at what value, remains that bank’s decision under the credit regulations in force.
Clause 1 of Article 8a imposes a further obligation that is easily overlooked: where an IP right does not yet satisfy the conditions for its value to be recorded as an asset in the accounting books, the owner must maintain a separate list for internal management purposes. This is an obligation, not a recommendation.
A transaction price database. Decree 100/2026 tasks the Ministry of Science and Technology with building a national database of IP transactions, covering assignments, licences, mortgages and capital contributions, together with transaction prices. The purpose is to make the market more transparent and to provide a reference point for valuation.
Over the longer term, this is the provision worth watching. The principal obstacle to contributing IP as capital in Vietnam has never been a legal prohibition, but the absence of a valuation basis acceptable to both parties to the transaction and to the state authorities. A transaction price database, once it holds enough data, addresses precisely that bottleneck. That will take time, however, so in the short term companies will still need to rely on independent valuation.
4. Investment Incentives Linked to Technology Content
Under the 2025 Investment Law and Decree 96/2026, entitlement to incentives depends on several factors at once: location, sector, investment scale and technology commitments. Two projects with the same level of capital may fall into different incentive tiers depending on the extent of technology transfer, research and development, and design activity the project carries out in Vietnam.
Of particular note for technology clients, Law No. 24/2026/QH16 removed research and manufacturing activities from the scope of conditional business lines.
The consequence is that applications have to be prepared differently. Previously, an incentive application mainly demonstrated capital scale and location. It now has to demonstrate technology content as well: what the technology is, who owns it, to whom it is transferred, how many personnel are trained, and what localisation rate applies. In effect, a company’s IP documentation becomes part of its investment application, rather than a separate record held by the legal department.
5. Technology Transfer: Earlier Appraisal and Decentralised Authority
The amended Technology Transfer Law contains two distinct changes that are often treated in practice as one.
First, on technology appraisal. For a project using technology subject to transfer restrictions, appraisal is now tied to the in-principle investment approval stage, rather than handled separately at a later stage of contract performance. Under Decree 101/2026, appraisal authority is determined by the level at which the project is approved: the State Appraisal Council for projects within the National Assembly’s authority, the Ministry of Science and Technology for projects within the Prime Minister’s authority, and provincial People’s Committees for the remainder.
Second, on licensing. Clause 11, Article 1 of the amending Law decentralises licensing authority for restricted-transfer technology to provincial People’s Committees. Previously, under Article 29 of the former law, this authority was concentrated at the Ministry of Science and Technology.
The Law also widens the concept of what may be transferred as technology, covering technical know-how, technological solutions and processes, models, algorithms, formulas, software, information and data. This reflects the reality that most technology value today lies in intangible assets rather than in the accompanying machinery and equipment.
On transitional provisions, one point deserves attention: a project using restricted-transfer technology that was approved before 1 April 2026 without technology appraisal must still undergo appraisal or consultation under Law No. 115/2025/QH15 if its technology content is amended after that date.
6. Outstanding Matters for Ongoing Consideration
First, on accounting. IP rights are recorded as an asset in the accounting books only once they satisfy the conditions under the accounting legislation, and detailed guidance on where that line falls has not been issued. Pending guidance, Clause 1 of Article 8a requires the owner to maintain a separate list for internal tracking.
Second, on incorporating first. Having the option does not mean it always suits. For projects with long preparation periods, projects involving land lease in industrial parks, projects in hi-tech parks, or projects whose objectives require consultation with other state agencies, incorporating before there is a firm basis for expecting the Investment Registration Certificate creates a legal entity that exists but has no approved project to carry out. In the early period of applying the Law, the traditional sequence remains safer for this group of projects.
Third, on coordination between regimes. A foreign investor implementing a technology-intensive project must now satisfy three legal regimes simultaneously: investment, intellectual property and technology transfer. All three only began operating together in 2026, so coordination between the authorities handling each element remains uneven across provinces.
Fourth, on the special investment procedure. Decree 96 does not clarify how a project partly inside and partly outside a zone is to be treated, that is, whether the special procedure may apply to the in-zone portion and the ordinary procedure to the remainder. This is a gap to watch in subsequent guidance.
Fifth, on the business line list. Law 24/2026 takes effect on 1 March 2027, so projects currently in preparation should be checked against both the list in force and the list that will replace it.